Week Ending 11/20/2026
The markets traded to multi-month lows as speculative selling continued last week. December and March futures traded within 8 cents of the contract lows we saw back in June. December futures ended the week 11 cents lower while March and May futures lost 8 cents. The funds are now short 61,862 corn and long 107,630 soybean contracts.
The markets tried to rally early in the week but turned lower on Wednesday when it became apparent that Agriculture products would be lower on the list of priorities at the APEC summit in China that President Trump is attending along with President Xi and President Putin. Details out of the meeting did not provide any clear outcomes for agricultural commodities. Trump said the Board of Trade has agreed to cut tariffs on $30 billion of trade from both sides, while he pushed China to deliver even more U.S. agricultural purchases. China has said the reciprocal rollback of tariffs is a requirement for it to make U.S. ag purchases aside from soybeans. There was an agreement to boost the supply of global energy products without any specific details.
Pair the summit news with a US Dollar that continues to run higher and the net result is lower exports and reduced demand for US grain. Weekly export sales continue to drag with the current pace 284 million or 9% below the pace needed to meet the USDA’s projections.
Producers remain hesitant to sell as prices continue to plummet and processors are improving their basis in an attempt to get grain to move. Some areas of the country have seen basis strengthen more than 25 cents in the last two weeks.
Harvest is mostly wrapped up, although there are still areas of OH, NE, IA, and the Dakotas trying to reach the finish line. We’ve had a few WASDEs trying to dial in yield expectations, but the final yield is still to be determined. Historically we do not see any yield adjustments in December, so we’re left to wait until January. We are now in a transition period where the supply side of the U.S. balance sheet is approaching its finale, and demand is about to take front and center.
Upcoming reports
| Date | Report |
| 11/26/2026 | No Markets |
| 11/27/2026 | Markets Close at 12:05 CT |
| 12/10/2026 | Crop Production |
| 1/12/2026 | Crop Production |
Week Ending 11/13/2026
Tuesdays WASDE report provided the fuel the markets had been looking for but only managed to move the markets fractionally higher by the end of the week. December corn ended the week 4 cents higher while March and May ended the week 2 and 1 cent higher. After establishing a net short position early in the week, the funds did manage to revert course and end the week long 7,295 corn contracts and long 141,727 soybean contracts.
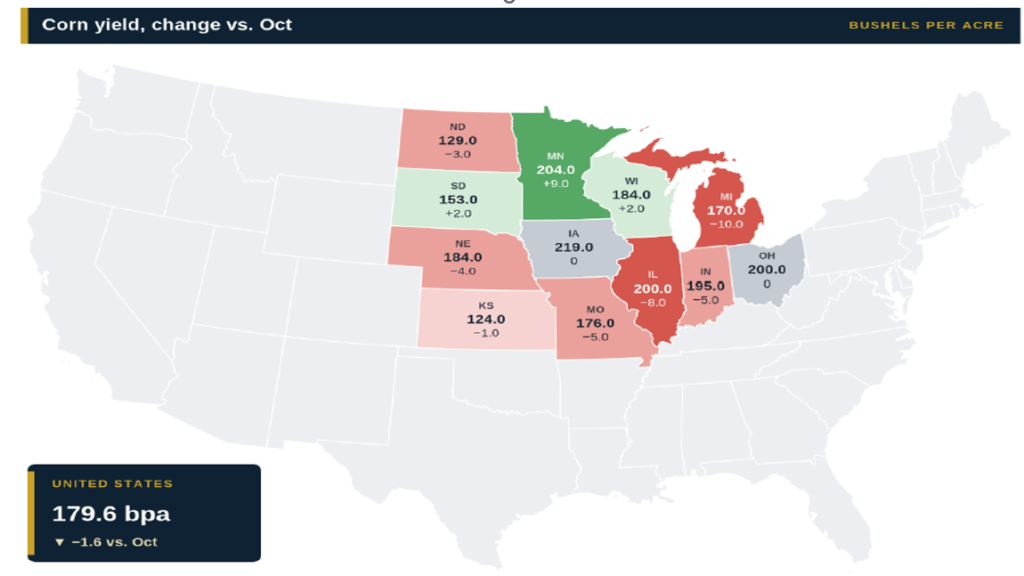
Corn ending stocks decreased 91 million bushels from last month to 1.758 billion as the result of a lower yield estimate which was pegged at 179.6 bushels per acre. Both feed and residual use along with export forecasts were lowered 25 mb each to accommodate the lower crop estimate. The domestic stocks/use ratio is now pegged at 10.82% vs. 11.34% in October.
USDA 2026 US Yield (Bushels per Acre)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 179.6 | 180.3 | 181.2 |
| Soybeans | 53.3 | 53.5 | 53.1 |
USDS 2026 Production (Billion Bushels)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 15.893 | 15.961 | 16.037 |
| Soybeans | 4.574 | 4.597 | 4.562 |
USDA 2026/27 US Carryout (Billion Bushels)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 1.758 | 1.840 | 1.849 |
| Soybeans | .300 | .331 | .315 |
| Wheat | .743 | .746 | .740 |
USDA 2026/27 World Carryout (Million Tonnes)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 281.94 | 281.44 | 280.44 |
| Soybeans | 123.5 | 124.73 | 124.28 |
| Wheat | 280.82 | 276.44 | 276.04 |
Below is a map showing the yield changes from the October to November report. Significant changes were seen in Michigan, Illinois and Minnesota with minor adjustments in several other top corn producing states.
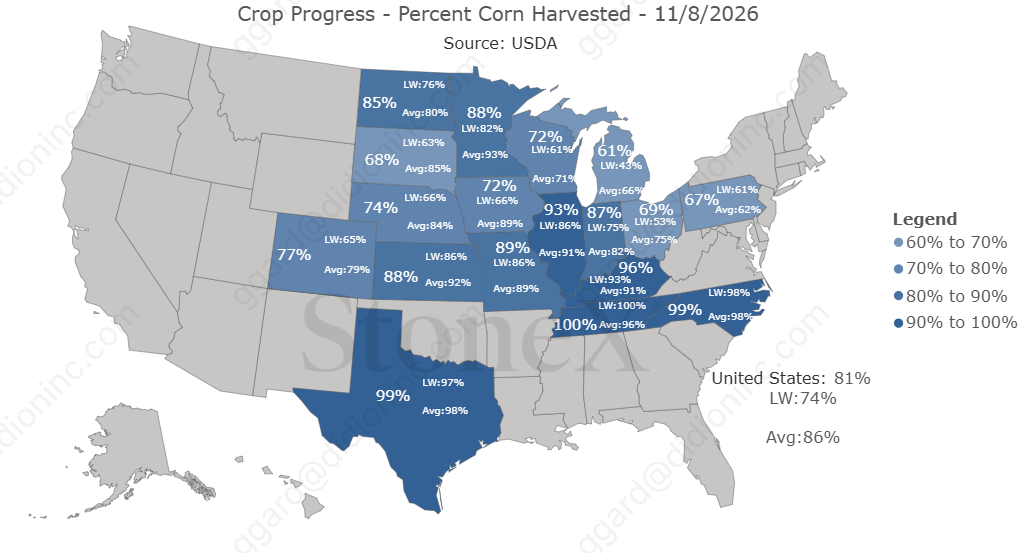
Corn harvest continues to lag the 5-year average despite decent progress over the last couple weeks. IA and South Dakota continue to show the slowest progress vs. average due to multiple rain events over the last month.
With the November WASDE behind us, the next major report will be the January WASDE which will give us the final yield for the 2026 crop. There will be a December WASDE, but the USDA only adjusts demand in this report with no adjustments to production. I believe the lows are in for the time being and look for the markets to trade sideways to higher over the next 2 months. A 1.758-billion-bushel carryout is sufficient, but the USDA’s latest revision is a good reminder that our supply cushion can change quickly.
Upcoming reports
| Date | Report |
| 12/10/2026 | Crop Production |
| 1/12/2027 | Crop Production |
Week Ending 11/6/2026
A meltdown in the equity markets following Tuesday’s election results spilled over into the commodity markets as the funds continue to liquidate the commodity space in a risk-off environment. December corn ended the week 7 cents lower while March and May futures ended the week 6 cents lower. As of Friday, the funds are long 8,795 corn contracts and 127,727 soybean contracts.
The USDA will release its November WASDE on Tuesday November 10th at 11:00am. It feels like the bias is for a slightly lower yield than the October report, but still north of 180 bushels per acre.
USDA 2026 US Yield (Bushels per Acre)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 180.3 | 181.2 | |
| Soybeans | 53.5 | 53.1 |
USDS 2026 Production (Billion Bushels)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 15.961 | 16.037 | |
| Soybeans | 4.597 | 4.562 |
USDA 2026/27 US Carryout (Billion Bushels)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 1.840 | 1.849 | |
| Soybeans | .331 | .315 | |
| Wheat | .746 | .740 |
USDA 2026/27 World Carryout (Million Tonnes)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 281.44 | 280.44 | |
| Soybeans | 124.73 | 124.28 | |
| Wheat | 276.44 | 276.04 |
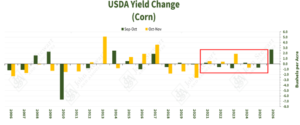
Roughly half the time we see the USDA move yields in the same direction in both the October and November reports. Recent years have shown less volatility in yield adjustments in November with 2023 as the outlier. This will most likely be the last adjustment we see prior to the final report in January as the USDA historically does not update production in its December report.
The U.S., Russia and Ukraine are scheduled to hold a trilateral meeting Tuesday November 10th, with an end of attacks and a potential grain export corridor among the topics to be discussed. China said it has been in contact with the U.S. and Russia about a meeting between the three country’s leaders at the APEC summit in China later in November.
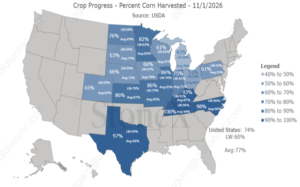
Corn harvest is largely done but there are pockets of delays in both east (OH/MI) & West (IA/NE/SD) that hold us behind average.
The WASDE Report and the Ukraine-Russia trilateral talks all happen on Tuesday, which will confirm market expectations or break them. The markets have been bearish over the last two months for multiple reasons. With prices near the June 30th lows I feel we are at or near the bottom and will start to reverse course in the next couple weeks.
Upcoming reports
| Date | Report |
| 11/9/2026 | Crop Progress |
| 11/10/2026 | Crop Production |
| 12/10/2026 | Crop Production |
Week Ending 10-30-2026
The corn markets continue their attempt to fend off bearish news as harvest plugs along. Harvest pressure, bearish soybean and wheat markets along with the upcoming election kept corn on the defensive this past week. December futures ended the week 8 cents lower while March and May futures closed 9 and 10 cents lower respectively. The funds have exited more than 200,000 of their long position in corn since the bearish October WASDE. The funds ended the week long 99,113 corn contracts and long 190,781 soybean contracts.
Export sales reported by the USDA showed another declining week, down .2 mmt (million metric ton) from last week and down .5 mmt from last year. Commitments are 23.5 mmt vs 35.4 mmt the same week a year ago. The USDA is forecasting only a 3.3 mmt decline year over year. Mexico’s purchases, or lack thereof, are a large share of the pullback. The US’s competitive advantage to Mexico remains in place but is slipping in other destinations.
Brazil’s producers are aggressively marketing their corn crop. Brazil’s first corn crop is 16% priced, the highest percent in five years. The second corn crop has been marketed at an average pace, and 13% of it is priced as of last week.
Rain is in the forecast for this week, with widespread 1–3 inches across the Midwest that should slow remaining harvest. For many this is welcome even if it pushes corn harvest further behind average as it will ease the pressure and allow end users and elevators to make some space. States with the most left include OH, MI, IA, NE, KS, and MN.
Harvest has been progressing by leaps and bounds over the past couple weeks. Last week’s report showed the crop was 60% complete compared to 44% the previous week. While still lagging the five-year average, things are moving along nicely thanks to an unseasonably warm fall.
We are just over a week away from the November WASDE which should have traders’ attention. Historically this report would not carry a lot of weight but given the big changes we saw in the October WASDE, many will be paying close attention to see if the USDA pulls back from their last report, piles on more bearish news or kicks the can. All three are equally in play, so play your cards close to your vest!
Upcoming reports
| Date | Report |
| 11/2/2026 | Crop Progress |
| 11/10/2026 | Crop Production |
Week Ending 10-16-2026
We had a weaker trade this past week as the markets focused on harvest progress. December corn ended the week 6 cents lower while March and May closed 8 cents lower. The funds ended the week long 227,925 corn contracts and long 227807 soybean contracts.
While the USDA estimates for the US crop continue to keep pressure on the markets as harvest progresses along, private estimates for Brazil’s crop added pressure. Conab (Brazil’s version of the USDA) is estimating a total corn crop for the upcoming season at 148 mmt (million metric ton) which is 9 mmt larger than the USDA’s current forecast. Conab puts the growth on a 4.9% expansion in acreage despite the discussions about rising costs associated with fuel and fertilizer. 9 mmt or 350 million bushels in extra supplies, if recognized by the USDA could have an impact on futures. This would be 350 million bushel more export-competing supplies and could translate to a smaller US export program.
Harvest progress had a 10% increase week over week and is currently 33% complete. This compares to 39% on average. Weather was favorable across most of the Midwest last week which should result in better progress in this afternoon’s report.
December futures closed below the 200-day moving average of $4.79 on Friday setting the tone for bearish trade in the coming week. The next support level in December corn is at $4.70 followed by $4.57. I could see us testing the first support level early this week, but don’t expect to reach the second without some outside news.
Upcoming reports
| Date | Report |
| 10/19/2026 | Crop Progress |
| 11/10/2026 | Crop Production |
