
Tuesdays WASDE report provided the fuel the markets had been looking for but only managed to move the markets fractionally higher by the end of the week. December corn ended the week 4 cents higher while March and May ended the week 2 and 1 cent higher. After establishing a net short position early in the week, the funds did manage to revert course and end the week long 7,295 corn contracts and long 141,727 soybean contracts.
Corn ending stocks decreased 91 million bushels from last month to 1.758 billion as the result of a lower yield estimate which was pegged at 179.6 bushels per acre. Both feed and residual use along with export forecasts were lowered 25 mb each to accommodate the lower crop estimate. The domestic stocks/use ratio is now pegged at 10.82% vs. 11.34% in October.
USDA 2026 US Yield (Bushels per Acre)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 179.6 | 180.3 | 181.2 |
| Soybeans | 53.3 | 53.5 | 53.1 |
USDS 2026 Production (Billion Bushels)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 15.893 | 15.961 | 16.037 |
| Soybeans | 4.574 | 4.597 | 4.562 |
USDA 2026/27 US Carryout (Billion Bushels)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 1.758 | 1.840 | 1.849 |
| Soybeans | .300 | .331 | .315 |
| Wheat | .743 | .746 | .740 |
USDA 2026/27 World Carryout (Million Tonnes)
| USDA November | Average Trade Est. | USDA October | |
| Corn | 281.94 | 281.44 | 280.44 |
| Soybeans | 123.5 | 124.73 | 124.28 |
| Wheat | 280.82 | 276.44 | 276.04 |
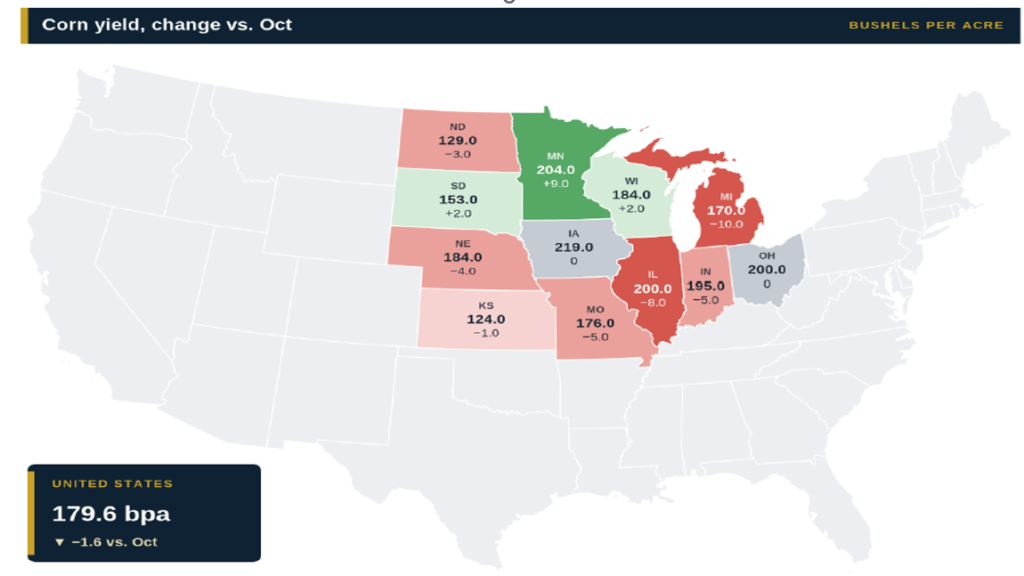
Below is a map showing the yield changes from the October to November report. Significant changes were seen in Michigan, Illinois and Minnesota with minor adjustments in several other top corn producing states.
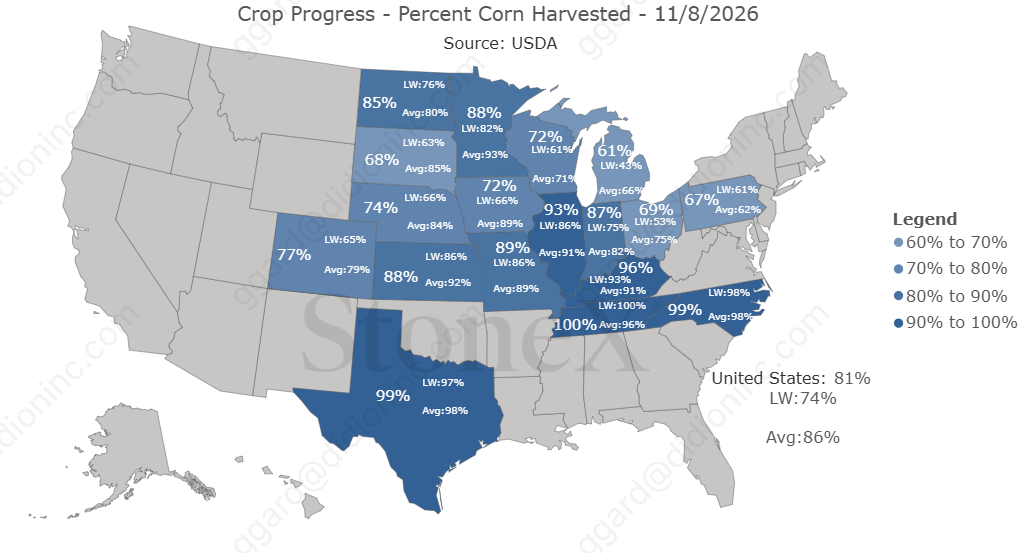
Corn harvest continues to lag the 5-year average despite decent progress over the last couple weeks. IA and South Dakota continue to show the slowest progress vs. average due to multiple rain events over the last month.
With the November WASDE behind us, the next major report will be the January WASDE which will give us the final yield for the 2026 crop. There will be a December WASDE, but the USDA only adjusts demand in this report with no adjustments to production. I believe the lows are in for the time being and look for the markets to trade sideways to higher over the next 2 months. A 1.758-billion-bushel carryout is sufficient, but the USDA’s latest revision is a good reminder that our supply cushion can change quickly.
Upcoming reports
| Date | Report |
| 12/10/2026 | Crop Production |
| 1/12/2027 | Crop Production |
